
Free online invoicing software
with KSeF support
The new Polish Deal will bring many changes for businesses, including quite significant ones for sole proprietorships. Some reforms will enter into force in the new tax year, while others will apply this year. What will change for entrepreneurs? What changes will the new Polish Deal bring, and which should you prepare for in advance? We explain.
The new Polish Deal and taxes – what entrepreneurs can expect
The Ministry of Finance has presented a bill that will substantially change taxation. Low earners will benefit, while entrepreneurs with high incomes will feel the reform strongly. The main tax changes are:
- The tax-free amount will rise to PLN 30,000;
- The first tax threshold will rise from PLN 85,528 to PLN 120,000 in annual income;
- Health insurance contributions will be 9% for those taxed under general rules and for governing bodies of legal persons, and one third of the lump-sum rate for those using lump-sum taxation;
- Health insurance contributions will not be deductible from tax;
- A so-called “middle-class relief” will be introduced, but by design it will not cover those earning income from civil-law contracts or business activity (including their own business);
- R&D relief and IP Box are to be combined;
- A “return relief” will be introduced for entrepreneurs moving their businesses to Poland or returning from abroad – for two years after returning they will pay only 50% of PIT.
When the reforms of the new Polish Deal take effect (from 1 January 2022), entrepreneurs, especially higher earners, will feel the effects in their wallets.

Subscribe to our newsletter
Leave your email address and receive guides supporting your business’s growth once a week

The new Polish Deal – tax under general rules
According to the Ministry of Finance, entrepreneurs can expect substantial tax changes. We present them below, in tables and charts for a clearer picture.
The new Polish Deal and tax under general rules:
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX-FREE AMOUNT / ROK |
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
3 000 PLN |
381 PLN |
182 PLN |
525 PLN |
6 231 PLN |
|
NEW POLISH DEAL |
3 000 PLN |
279 PLN |
510 PLN |
5 100 PLN |
4 260 PLN |
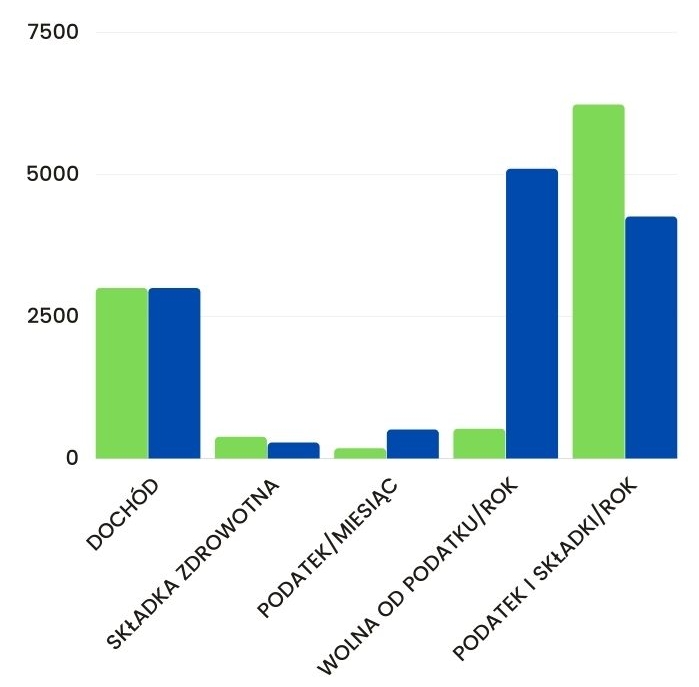 Green: current level. Blue: projected level after the new Polish Deal.
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX-FREE AMOUNT / ROK |
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
7 000 PLN |
381 PLN |
862 PLN |
525 PLN |
14 391 PLN |
|
NEW POLISH DEAL |
7 000 PLN |
630 PLN |
1190 PLN |
5 100 PLN |
16 740 PLN |
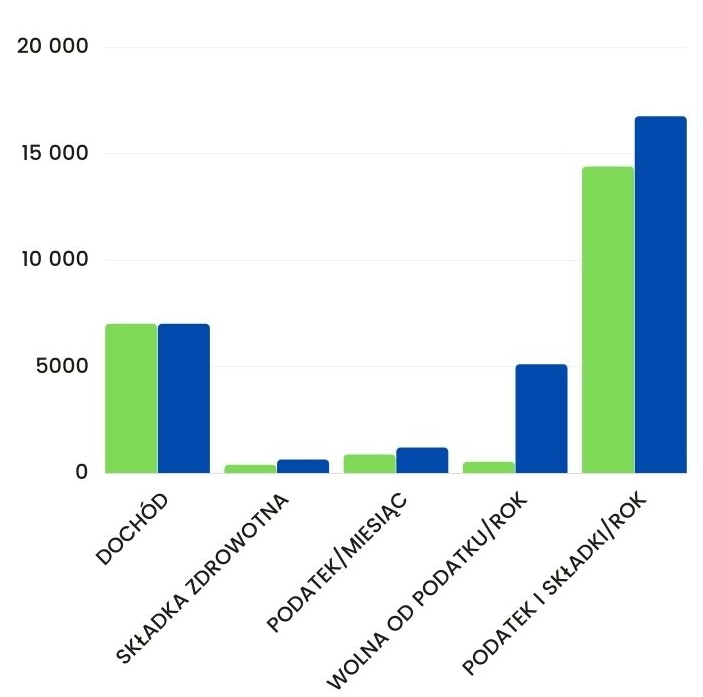 Green: current level. Blue: projected level after the new Polish Deal.
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX-FREE AMOUNT / ROK |
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
20 000 PLN |
381 PLN |
3 072 PLN |
- |
67 512 PLN |
|
NEW POLISH DEAL |
20 000 PLN |
1 800 PLN |
3 400 PLN |
- |
74 540 PLN |
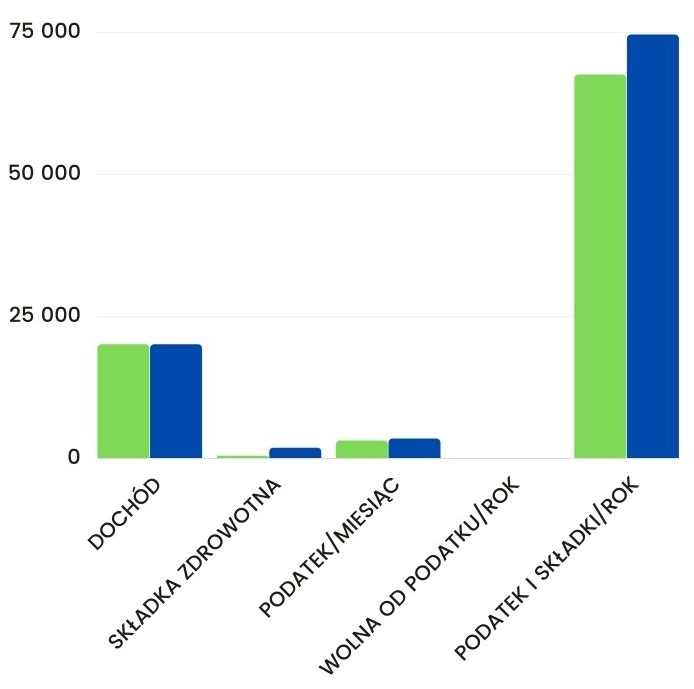 Green: current level. Blue: projected level after the new Polish Deal.
Flat-rate income tax and the new Polish Deal
The situation differs somewhat for entrepreneurs paying flat-rate income tax: the differences concern ZUS contributions and their settlement. The new Polish Deal affects this group as follows:
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
3 000 PLN |
381 PLN |
242 PLN |
7 476 PLN |
|
NEW POLISH DEAL |
3 000 PLN |
279 PLN |
570 PLN |
10 188 PLN |
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
7 000 PLN |
381 PLN |
1 002 PLN |
16 596 PLN |
|
NEW POLISH DEAL |
7 000 PLN |
630 PLN |
1 330 PLN |
23 520 PLN |
|
CONTEXT |
DOCHÓD / MIESIĄC |
HEALTH CONTRIBUTION |
TAX / MIESIĄC
|
TAX AND HEALTH CONTRIBUTION BURDEN / ROK |
|
CURRENTLY |
20 000 PLN |
381 PLN |
3 472 PLN |
46 236 PLN |
|
NEW POLISH DEAL |
20 000 PLN |
1 800 PLN |
3 800 PLN |
67 200 PLN |
The calculations above exclude social insurance contributions of about PLN 1,000, which entrepreneurs pay now and will continue to pay.
The new Polish Deal and lump-sum tax
The new Polish Deal will make few changes to lump-sum rates. The major reform concerns health contributions for entrepreneurs using lump-sum taxation: the contribution will be one third of the lump-sum rate. Paid health contributions will also no longer be deductible from tax.
The new Polish Deal – sole proprietorships
Despite claims that 18,000,000 people will benefit, the new Polish Deal is not good news for many sole proprietors. The legislature also seeks to discourage civil-law contracts. Particularly painful is the exclusion of business and civil-law contract income from the “middle-class relief”.
The relief applies to annual earnings of PLN 68,412–133,692 (PLN 5,700–11,140 monthly), but only under employment contracts. Entrepreneurs in that bracket cannot offset losses caused by the loss of the health contribution deduction. This raises the question whether it is better to establish a company or move a sole proprietorship outside Poland, for example to the Czech Republic. We invite anyone asking that question to contact us. TaxCoach experts will suggest the most advantageous solution.
Interested in this article? Explore our services and see how we can help:
Our specialists can help you put this knowledge into practice.

Interested in this article?
Enter your email address and once a week you will receive practical materials and tips to help you grow your business.

Book a free consultation
Grow your business with accounting combined with advisory services:

or