

Free online invoicing software
with KSeF support
During job interviews, we often hear: “Choose how we work together: employment contract or B2B.” But is it really that simple? B2B is a popular form of contract for services provided through a sole proprietorship. It is particularly common in IT, legal services, journalism and sales. Its main advantages are considerable freedom for the parties to shape the agreement (without most restrictions associated with an employment contract) and favourable tax aspects. Hence both businesses and contractors frequently choose B2B.
Choosing a tax method
A person providing services through a business may choose one of three income-tax methods, discussed below. For each, the tax and health insurance contribution have been calculated as examples using these assumptions:
- PLN 150,000 – revenue,
- PLN 20,000 – costs,
- PLN 15,798 – social insurance contributions paid during the year,
- for lump-sum tax, an 8.5% rate.
Importantly, when providing B2B services to a current or former employer (in the given year or previous year), the taxpayer cannot choose flat tax or lump-sum tax, nor ZUS relief (start-up relief or reduced ZUS contributions).

Accounting that understands your business
Leave your email address and receive guides supporting your business’s growth once a week

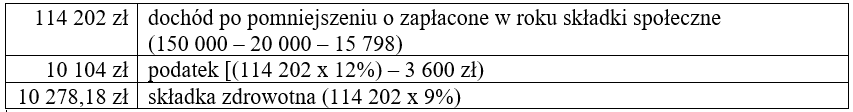
Progressive tax scale
This method has a tax-free amount of PLN 30,000 of income. Above that amount and up to PLN 120,000, the rate is 12%; income above the threshold is taxed at 32%. Every amount of income is subject to a 9% health contribution. This method is therefore not advantageous at high incomes.
Example:
Flat tax
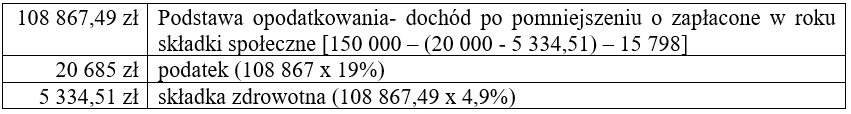
Tax under this method is 19% (with no tax-free amount) plus a 4.9% health contribution.
Health contributions of up to PLN 10,200 may be included in tax-deductible costs (including them in costs is more advantageous).
Example:
Under the general rules and flat tax there is a minimum health contribution. In 2023 it was PLN 314.10 for January through June and PLN 324 for the remaining months.
Lump-sum tax
Under lump-sum taxation, revenue is the tax base, unlike the tax scale and flat tax, where the tax base is income.
The lump-sum rate depends on the taxpayer's activities. It should be determined under Article 12 of the Lump-Sum Tax Act.
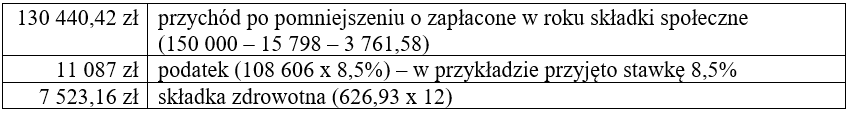
Besides tax, a health contribution is due. Its amount depends on annual revenue in three bands. The monthly amounts below apply to 2023. For revenue:
- up to PLN 60,000 – the health contribution is PLN 376.16,
- above PLN 60,000 and up to PLN 300,000 – PLN 626.93,
- above PLN 300,000 – PLN 1,128.48.
The health contribution is set for the tax year and adjusted annually based on increases in the average wage.
The base for tax and health contributions is revenue less social insurance contributions paid in the given month and 50% of the health contribution paid.
Example:

If you found this article interesting, explore our tax advisory services and read how we can help you:
Summary
All the above calculations are examples only, and each case should be considered in detail. However, on these assumptions, lump-sum tax is clearly the most advantageous method.

Interested in this article?
Enter your email address and once a week you will receive practical materials and tips to help you grow your business.

Book a free consultation
Grow your business with accounting combined with advisory services:

or



